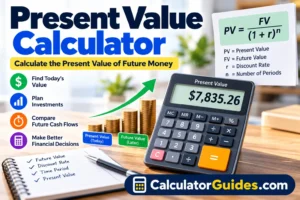
Present Value Calculator-A Present Value Calculator helps you find out how much a future amount of money is worth today. It uses the expected interest rate and the time you have to wait to receive the money.Calculate important financial figures with our interest, savings, share market and investment calculators.
A Present Value Calculator helps you find out how much a future amount of money is worth today. It uses the expected interest rate and the time you have to wait to receive the money.
For example, imagine you will receive $10,000 five years from now. Is that money worth $10,000 today? Not exactly. If you have money today, you may be able to invest it and earn a return before those five years are over.
This is the basic idea behind the time value of money.
Our Present Value Calculator at CalculatorGuides.com makes this calculation simple. Enter your future amount, discount rate, and time period to estimate its value today.
Whether you are planning an investment, comparing financial options, saving for retirement, or evaluating future cash flows, this calculator can help you make better-informed financial decisions.
What Is a Present Value Calculator?
A Present Value Calculator is an online financial tool that calculates the current worth of money you expect to receive in the future.
Present value is based on the idea that money available today can earn interest or investment returns. Because of this, a future payment may be worth less today than its stated amount.
The present value calculation uses three main inputs:
- Future Value (FV): The amount of money you expect to receive in the future.
- Discount Rate (r): The annual rate used to calculate how much the future money is worth today.
- Time Period (n): The number of years or periods until you receive the money.
For example, if you expect to receive $20,000 in five years, you can use a present value calculator to estimate how much that future payment is worth today at a selected discount rate.
The result depends on the discount rate you choose. A higher discount rate generally produces a lower present value, while a lower discount rate produces a higher present value.
Present Value Formula
The present value formula is used to convert a future amount of money into its value today.
The standard formula for a single future payment is:
[
PV=\frac{FV}{(1+r)^n}
]
Where:
- PV = Present Value
- FV = Future Value
- r = Discount rate per period
- n = Number of periods
The discount rate and number of periods must use the same time unit. For example, if you use an annual discount rate, the number of periods should normally be expressed in years.
Example of the Present Value Formula
Suppose you want to receive $10,000 after five years. You use a discount rate of 5% per year.
The values are:
- Future value = $10,000
- Annual discount rate = 5%, or 0.05
- Time period = 5 years
Using the formula:
[
PV=\frac{10,000}{(1+0.05)^5}
]
[
PV=\frac{10,000}{1.27628}
]
[
PV\approx $7,835.26
]
This means that $10,000 received five years from now has a present value of approximately $7,835.26 at a 5% annual discount rate.
The result does not mean you will necessarily earn this amount. It shows the current equivalent of the future payment under the selected discount-rate assumption.
How to Use the Present Value Calculator
Using a present value calculator is easy. Follow these steps to calculate the present value of a future amount.
Step 1: Enter the future value
Enter the amount of money you expect to receive later. For example, you can use $5,000, $10,000, or $100,000.
Step 2: Enter the discount rate
Add the annual discount rate as a percentage. For example, enter 5 for a 5% annual discount rate.
Step 3: Enter the time period
Enter the number of years until you expect to receive the money. If your calculator supports other periods, make sure the rate matches the selected period.
Step 4: Click Calculate
The calculator uses your inputs and the present value formula to calculate the estimated value today.
Step 5: Review the result
Check the present value and compare it with the future amount. You can change the discount rate or time period to see how the result changes.
For the most useful comparison, keep the future amount the same while testing different rates and time periods.
Present Value Calculation Examples
Let’s look at a few examples to understand how present value works.
Example 1: Present Value of $10,000
Suppose you will receive $10,000 after three years, and your discount rate is 5% per year.
| Details | Value |
|---|---|
| Future value | $10,000 |
| Discount rate | 5% |
| Time period | 3 years |
| Present value | $8,638.38 |
The present value is approximately $8,638.38. Under a 5% annual discount rate, this is the amount today that is mathematically equivalent to receiving $10,000 in three years.
Example 2: Present Value of $50,000
Imagine you will receive $50,000 after 10 years. You want to calculate its present value using a 6% annual discount rate.
| Details | Value |
|---|---|
| Future value | $50,000 |
| Discount rate | 6% |
| Time period | 10 years |
| Present value | $27,919.74 |
The present value is approximately $27,919.74.
This example shows how a future amount can have a much lower present value when the waiting period and discount rate are higher.
Example 3: Present Value of $100,000
Suppose you expect to receive $100,000 after 10 years and use a 5% annual discount rate.
| Details | Value |
|---|---|
| Future value | $100,000 |
| Discount rate | 5% |
| Time period | 10 years |
| Present value | $61,391.33 |
At a 5% discount rate, $100,000 received after 10 years has a present value of approximately $61,391.33.
These examples assume annual discounting and a single future payment. Actual investment decisions may require additional factors, such as risk, taxes, fees, and inflation.
Present Value Calculator by Interest Rate
The discount rate plays an important role in present value calculations. To understand its effect, let’s calculate the present value of $10,000 received after five years at different annual discount rates.
| Annual Discount Rate | Present Value |
|---|---|
| 2% | $9,057.31 |
| 3% | $8,626.09 |
| 5% | $7,835.26 |
| 7% | $7,129.86 |
| 10% | $6,209.21 |
As the table shows, the present value decreases when the discount rate increases.
This happens because a higher discount rate means you require a greater return to consider a future payment equivalent to money available today.
The appropriate discount rate depends on the purpose of the calculation. It may reflect an expected investment return, a required rate of return, or another financial assumption.
Present Value vs. Future Value
Present value and future value are closely related, but they answer different questions.
Present value (PV) tells you how much a future amount is worth today.
Future value (FV) tells you how much money you may have at a future date if an amount grows at a selected rate.
| Feature | Present Value | Future Value |
|---|---|---|
| Main purpose | Calculate today’s equivalent | Estimate a future amount |
| Starting point | Future money | Money available today |
| Common inputs | Future value, discount rate, time | Current amount, growth rate, time |
| Typical use | Investment evaluation | Savings and investment planning |
| Formula | (PV=FV/(1+r)^n) | (FV=PV(1+r)^n) |
For example, if you want to know how much you need to invest today to reach $50,000 in 10 years, a present value calculator can help.
If you already have $20,000 and want to estimate its value after 10 years, a future value calculator is more appropriate.
Present Value of an Annuity
Sometimes, you receive money in regular payments instead of receiving one large amount. These payments are called an annuity when they follow a defined payment schedule.
The Present Value of an Annuity Calculator estimates the current value of a series of equal payments.
For an ordinary annuity, where payments occur at the end of each period, the formula is:
[
PV=PMT\times\frac{1-(1+r)^{-n}}{r}
]
Where:
- PV = Present value of the payment series
- PMT = Payment amount per period
- r = Discount rate per period
- n = Total number of payments
For example, suppose you expect to receive $1,000 at the end of each year for five years, using a 5% annual discount rate.
[
PV=1,000\times\frac{1-(1.05)^{-5}}{0.05}
]
The present value of these payments is approximately $4,329.48.
This means the five future payments have a combined present value of about $4,329.48 at a 5% discount rate.
If payments occur at the beginning of each period instead, the calculation changes. This arrangement is called an annuity due.
Present Value of a Perpetuity
A perpetuity is a series of equal payments that continues indefinitely, assuming the payments and discount rate meet the formula’s conditions.
The basic present value formula for a level perpetuity is:
[
PV=\frac{C}{r}
]
Where:
- PV = Present value
- C = Payment received each period
- r = Discount rate per period
For example, if an investment pays $1,000 annually forever and the discount rate is 5%, its value under this simplified model is:
[
PV=\frac{1,000}{0.05}=$20,000
]
This formula assumes the first payment occurs one period from now and that the payments and discount rate remain constant. A growing perpetuity uses a different formula and requires the growth rate to be lower than the discount rate.
Why Is Present Value Important?
Present value is useful in many areas of personal finance, investing, and business planning.
1. Investment Planning
Investors can use present value to estimate the current worth of future payments from an investment.
It can help when comparing different investments that provide money at different times.
2. Retirement Planning
Present value can help you understand how much today’s savings may be worth relative to future retirement income.
It is also useful when estimating how much money you may need today to fund a series of future expenses.
3. Business Valuation
Businesses use present value methods to evaluate future cash flows from projects, assets, and investment opportunities.
Discounted cash flow analysis is a common valuation method that applies present value concepts to multiple expected cash flows.
4. Loan and Payment Analysis
Present value calculations can help compare the value of future payment streams. However, a standard present value calculator is not a complete loan payment calculator.
5. Financial Decision-Making
Present value helps people compare payments received at different times using a consistent financial assumption.
It can also make the effects of time and discount rates easier to understand.
What Is the Difference Between Present Value and Net Present Value?
Present value and net present value are related financial concepts, but they are not identical.
Present value calculates the value today of a future payment or series of payments.
Net present value (NPV) takes the present value of future cash inflows and subtracts the initial investment and any other relevant cash outflows.
A simplified NPV formula is:
[
NPV=PV\text{ of future cash flows}-\text{Initial Investment}
]
For example, if a project has future cash inflows with a present value of $50,000 and requires an initial investment of $40,000, its simplified net present value is $10,000.
A positive NPV means the project’s discounted cash inflows exceed its included cash outflows under the selected assumptions. It does not guarantee that the project will succeed.
Use a Net Present Value Calculator when you need to evaluate a project with an initial cost and multiple future cash flows.
What Discount Rate Should You Use?
There is no single discount rate that works for every present value calculation.
The correct rate depends on what you are trying to measure.
- Personal financial planning: You might use an expected investment return or another suitable planning assumption.
- Business projects: A business may use its cost of capital or a project-specific required return.
- Investment valuation: The rate should reflect the risk and timing of the expected cash flows.
- Comparing payment options: Use a consistent rate that reflects the purpose of the comparison.
A higher discount rate reduces present value, while a lower discount rate increases it.
Do not choose a discount rate only because it produces a preferred result. The rate should have a reasonable basis and match the cash flows being evaluated.
Limitations of a Present Value Calculator
A present value calculator is useful, but the result depends on the assumptions you enter.
The discount rate may change: Your actual investment return may be higher or lower than expected.
Future payments may be uncertain: Some payments depend on business performance, market conditions, or other factors.
Inflation matters: A nominal discount rate and nominal cash flows should be compared consistently. Inflation-adjusted calculations require real rates and real cash flows.
Taxes and fees may affect value: A basic calculator may not include investment costs, taxes, or transaction fees.
Timing matters: Payments at the beginning of a period have a different present value from payments at the end of the period.
For these reasons, use the result as a financial estimate rather than a guarantee.
Frequently Asked Questions
1. What is a Present Value Calculator?
A Present Value Calculator estimates how much a future payment is worth today using the future amount, discount rate, and time period.
2. How do I calculate present value?
Use the formula (PV=FV/(1+r)^n). Divide the future value by one plus the discount rate raised to the number of periods.
3. What is the present value of $10,000 after five years?
At a 5% annual discount rate, the present value of $10,000 received after five years is approximately $7,835.26.
4. What happens when the discount rate increases?
The present value generally decreases when the discount rate increases, assuming the future amount and time period remain unchanged.
5. What is the difference between PV and FV?
Present value calculates today’s equivalent of future money. Future value estimates how much money available today may grow to in the future.
6. Can I calculate the present value of monthly payments?
Yes. You can calculate the present value of monthly payments by using the monthly discount rate and the total number of monthly payments. The formula must match the payment timing.
7. What is the present value of an annuity?
It is the current value of a series of future payments, discounted using a selected rate. The result depends on the payment amount, payment frequency, discount rate, and number of payments.
8. What is the difference between present value and net present value?
Present value measures the current value of future cash flows. Net present value subtracts the relevant investment costs and cash outflows from the present value of future cash inflows.
9. Is a higher present value better?
A higher present value means the future payment or cash flow has a higher calculated value today under the selected assumptions. Whether it is better depends on the investment cost, risk, and other financial factors.
10. Is the Present Value Calculator free to use?
If the calculator is available free on CalculatorGuides.com, you can use it to estimate present value without manually applying the formula.
Conclusion
A Present Value Calculator helps you understand what future money is worth today. By entering the future amount, discount rate, and time period, you can calculate present value quickly and compare different financial scenarios.
Present value is useful for investment planning, retirement calculations, business valuation, and evaluating future payments. You can also apply the same concept to annuities and other regular cash flows.
The most important point is to use a reasonable discount rate and understand the assumptions behind the result.
Use the Present Value Calculator at CalculatorGuides.com to estimate the current value of future money and make more informed financial decisions.
Disclaimer: This article is for educational purposes only and does not provide financial, tax, or investment advice. Calculator results depend on the assumptions entered and should not be treated as guaranteed investment outcomes.